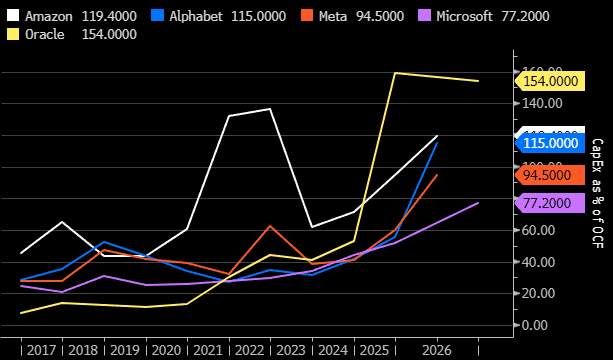
Oracle, Google, and Amazon all went cashflow negative in 2026. Meta is close. The cause is AI capital expenditure consuming nearly every dollar of operating cashflow these companies generate. Microsoft's AI revenue, dominated roughly 70% by OpenAI sales, accounts for only around 7% of total FY26 revenue. The buildout is expensive. The returns are not arriving.
The structural problem is this: AI chips cost enormous sums, data centers take years to build and energize, and the services running on that hardware are not generating revenue proportional to the spend. Hyperscalers built their business models on lean operating costs and low capex. That model is gone. Google posted its first-ever negative free cash flow quarter. Amazon's AWS is growing, but free cash flow turned negative on record AI spending. A trillion dollars in backlog commitments from Anthropic and OpenAI alone has not eased the cash burn.
The full piece goes deeper into the 'neocloud' layer, companies conjured from cryptocurrency mining operations or raised from scratch to buy NVIDIA and Broadcom chips and build data centers funded by debt. Their capex rivals the hyperscalers. Their revenue base does not. Zitron's argument is not that AI is worthless but that the financial architecture supporting the buildout is structurally precarious, and the numbers he cites make that case worth examining in full.
[READ ORIGINAL →]